
How much down payment do I need in Northwest Indiana?
The lender worksheet sat on the Suite B table next to a Crown Point coffee.
Three lines.
Down payment.
Closing costs.
Cash left for moving day.
That is the real question Northwest Indiana buyers ask.
Not a Facebook myth that every house needs twenty percent.
Not a promise that zero down is free money.
Not a percent pulled from a 2019 memory.
We are brokers at Realest Realty in Crown Point.
Our office is at 112 S. Main St., Suite B.
We are licensed in Indiana and Illinois.
Call Sash at (219) 808-1520.
Live inventory stays on Realest listings.
Start a conversation on Realest contact.
Buyers who want the shop path use How to buy with the shop.
Sellers who want the shop path use How to sell with the shop.
Sellers who want a value read go to RealestValues.com.
Short version.
Most financed buyers in Northwest Indiana need some cash at closing.
How much depends on the loan program, the house price, credit, and reserves.
A common floor for eligible conventional programs is about 3 percent down.
FHA is often 3.5 percent when you qualify.
VA and USDA can be 0 percent for eligible buyers and properties.
Twenty percent is still useful because it often skips private mortgage insurance on a conventional loan.
It is not a law.
Honest catch.
The June 2026 NWI MLS median of $299,000 is region context.
It is not your house.
Average 34 days on market does not set your down payment.
Freddie Mac put the 30-year fixed at 6.76 percent as of September 10, 2026.
That rate shapes monthly payment.
It does not invent your cash-to-close number.
What down payment means in plain English
Down payment is the cash you put toward the purchase price at closing.
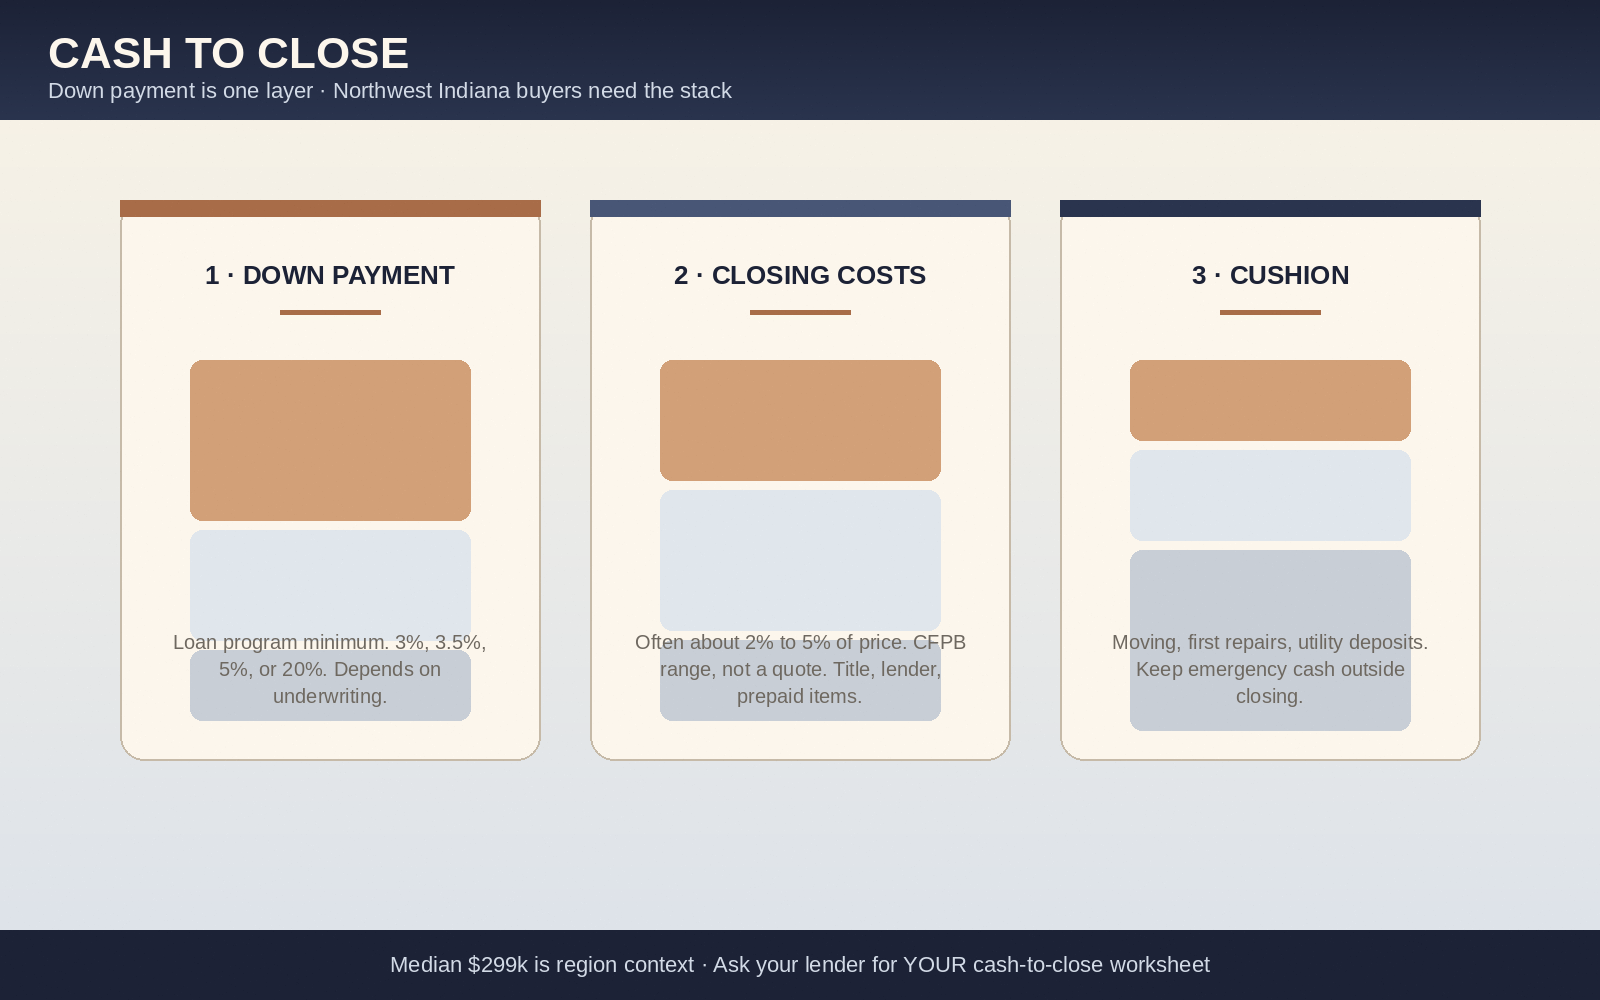
It is separate from closing costs.
Closing costs are the fees and prepaid items that finalize the loan and the deed.
The Consumer Financial Protection Bureau says closing costs often run about 2 percent to 5 percent of the purchase price, not including the down payment.
That is a planning range.
It is not a quote for any Crown Point, Munster, or Valparaiso closing.
Your lender builds a cash-to-close worksheet.
That sheet is the number that matters.
Example math on the June 2026 NWI median
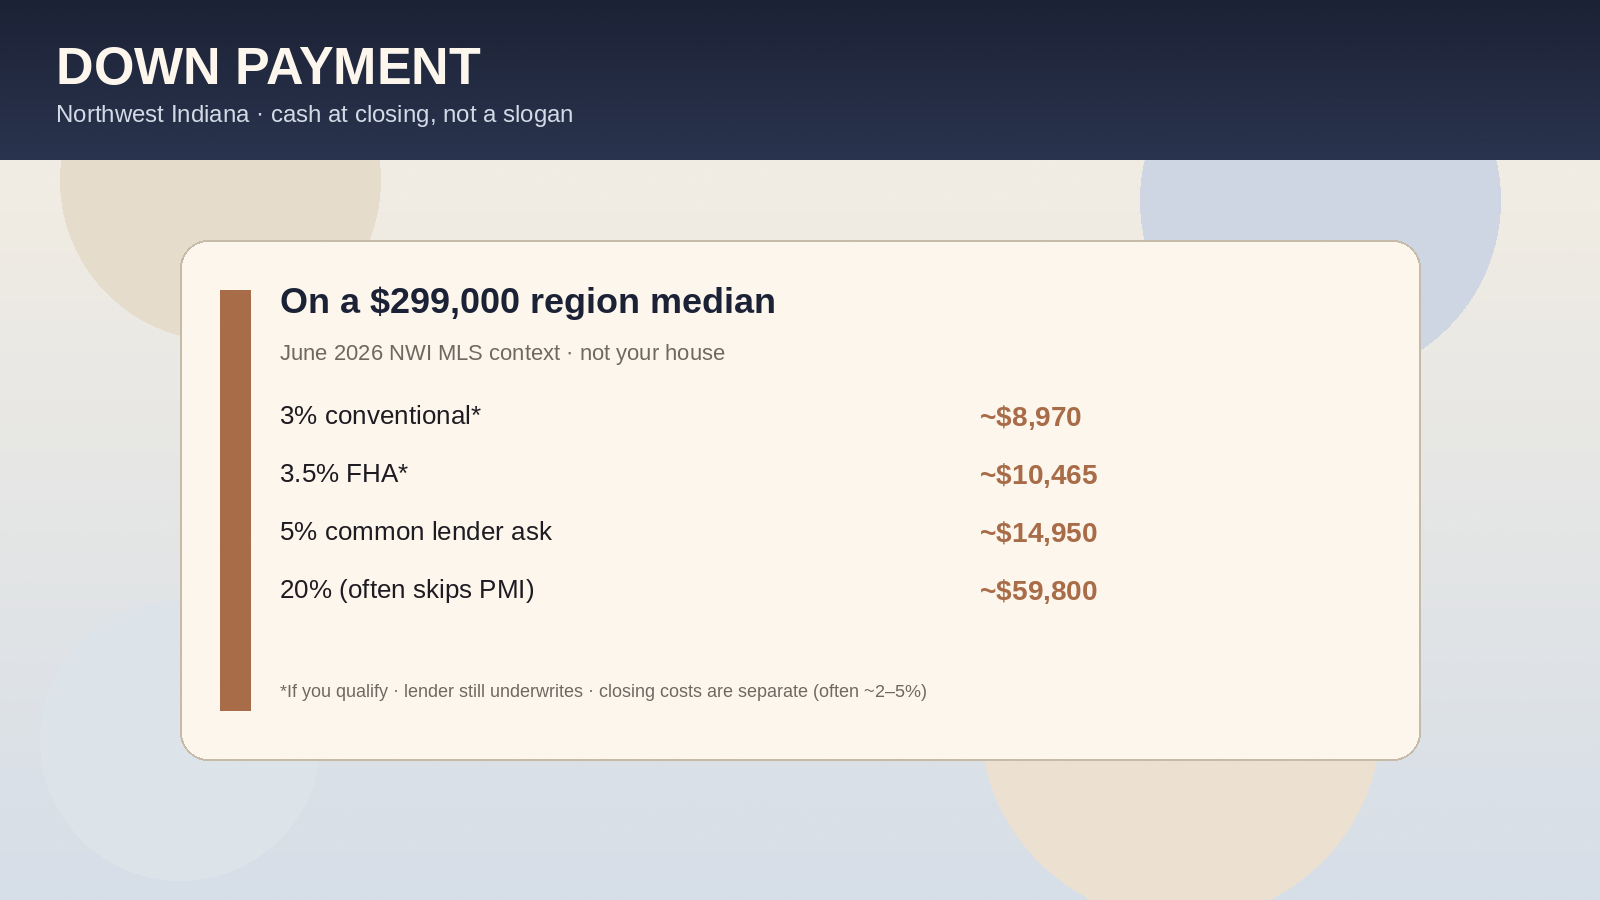
Use the June 2026 NWI MLS median of $299,000 only as a whiteboard.
| Down payment lane | Rough cash for down only |
|---|---|
| 3% conventional (if eligible) | about $8,970 |
| 3.5% FHA (if eligible) | about $10,465 |
| 5% | about $14,950 |
| 20% | about $59,800 |
Add closing costs on top.
At 2 percent to 5 percent of $299,000, that is roughly $5,980 to $14,950 more.
Then keep a cushion for moving, first repairs, and deposits.
Do not empty every account to hit a down payment target.
Lenders look at reserves.
Loan lanes buyers actually compare
Conventional loans.
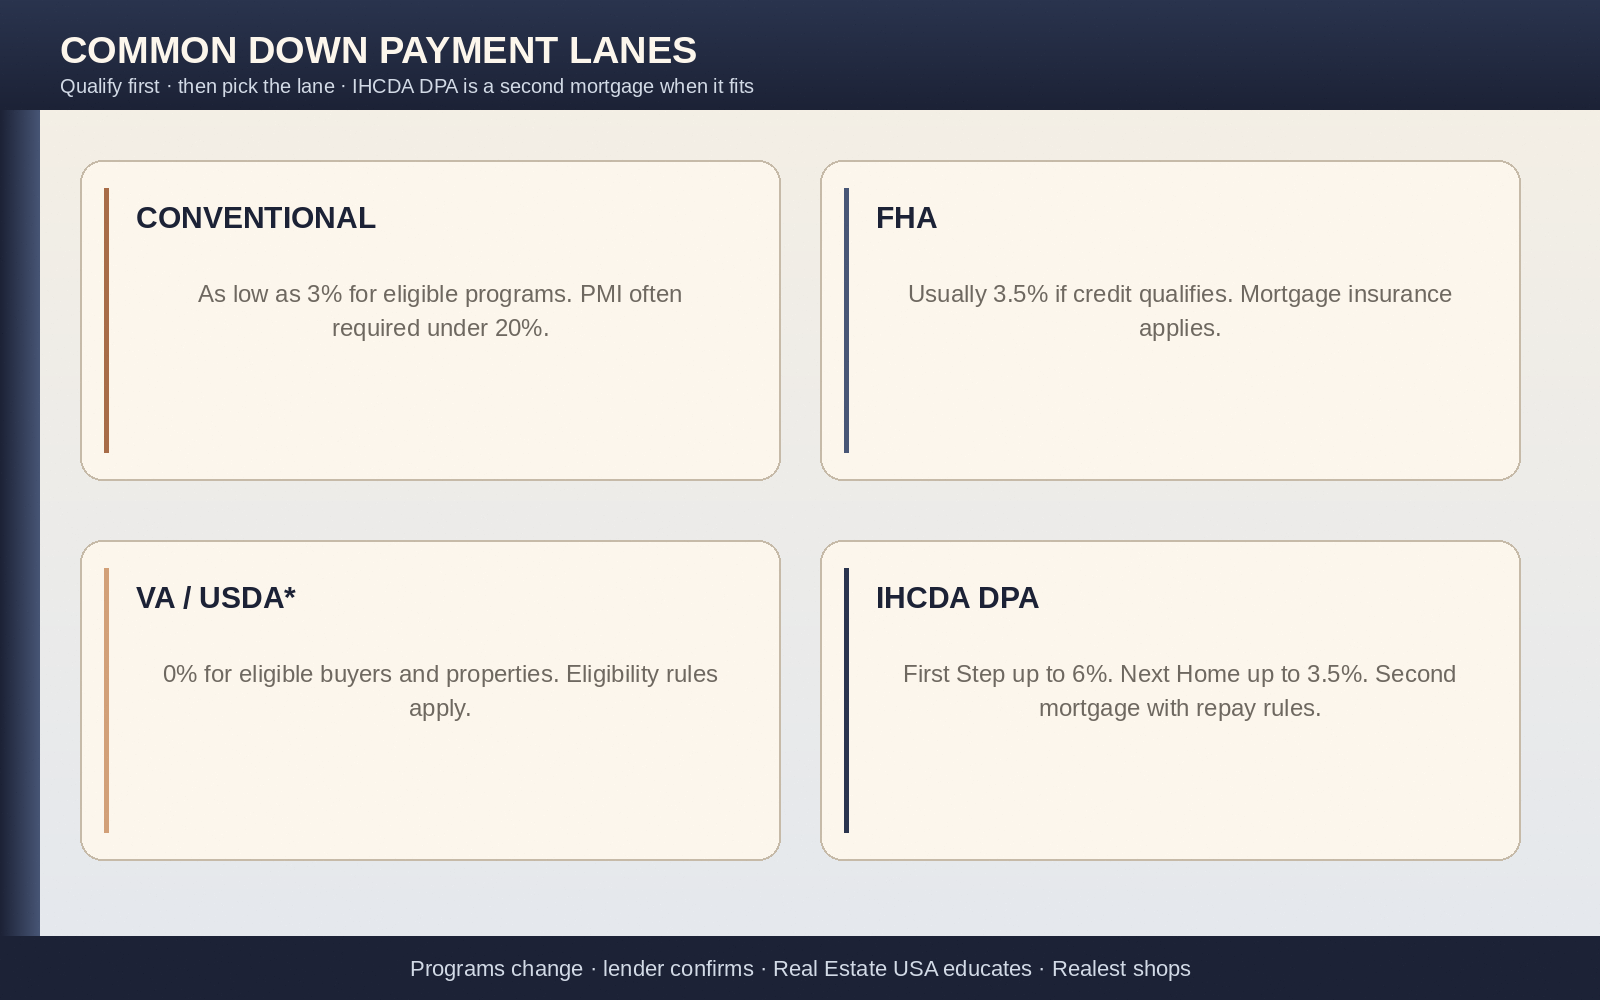
Eligible programs can allow as little as 3 percent down.
Under 20 percent, private mortgage insurance is common until you reach the lender’s threshold.
FHA loans.
HUD guidance puts the minimum required investment at 3.5 percent of the lesser of price or value for most eligible borrowers.
Lower credit bands can require more.
FHA also carries mortgage insurance.
VA loans.
Eligible veterans, service members, and some surviving spouses may buy with 0 percent down when the property and lender allow it.
There can still be a funding fee and closing costs.
USDA loans.
Eligible rural properties and income limits can allow 0 percent down.
Parts of Lake, Porter, and LaPorte Counties can qualify or fail the map depending on the address.
Check the property, not the rumor.
Indiana down payment help through IHCDA
Indiana Housing and Community Development Authority runs purchase programs with down payment assistance through participating lenders.
First Step is aimed at eligible first-time buyers or purchases in targeted census tracts.
Program guides describe down payment assistance up to 6 percent of the lower of price or appraised value as a non-forgivable second mortgage with no monthly payment on that second.
Next Home offers down payment assistance commonly described at 2.5 percent or 3.5 percent of the lower of price or value, also through a second mortgage structure, without a first-time buyer requirement on that product line.
Details, income limits, purchase-price caps, and repay rules change.
We do not invent your eligibility.
A participating lender confirms whether First Step, Next Home, or another lane fits your file.
Ask early.
DPA that shows up two weeks before closing is a stress test, not a plan.
What else eats cash at closing
Appraisal.
Inspection.
Title and escrow fees.
Prepaid taxes and insurance.
Homeowners association dues if the property has them.
Buyer-broker compensation after the NAR practice changes.
Your written buyer agreement may create a pay obligation.
You can still negotiate for a seller contribution in the offer.
Seller credits and lender limits share one math problem with your down payment.
Read the sibling page: Do buyers pay real estate commission now in Northwest Indiana?
How to choose a number without guessing
1. Pick a realistic house range for the towns you will actually drive on a Tuesday.
2. Ask a lender for a cash-to-close estimate at 3 percent, 3.5 percent, 5 percent, and 20 percent.
3. Ask whether IHCDA First Step or Next Home is even on the table for your income and the property.
4. Subtract moving and emergency cash before you spend every dollar on down payment.
5. Then shop houses that match the worksheet, not the other way around.
Browse live inventory on Realest listings after the worksheet exists.
Use How to buy with the shop for the Realest path.
The first-time buy guide sits beside this page: How do I buy a house in Northwest Indiana for the first time?
Hiring help: How to hire a Realtor in Northwest Indiana.
Relocators: Moving to Northwest Indiana.
Lived scene from South Main
A buyer walked in with a screenshot that said twenty percent is required.
We pulled the whiteboard.
Three percent.
Three point five.
Five.
Twenty.
Then closing costs.
Then reserves.
They were not ready for twenty percent.
They were ready for a conventional three percent lane if credit held, plus closing costs, plus a real cushion.
We sent them to a lender the same afternoon.
They came back with a worksheet.
Then we looked at Crown Point and Schererville listings that fit the number.
Paper first.
House second.
Honest catch
Do not treat the June median as your purchase price.
Do not ignore closing costs because a TikTok skipped them.
Do not count gift funds until the lender says the gift letter works.
Do not assume IHCDA DPA is free money.
It is usually a second mortgage with rules.
Do not sign a buyer agreement pay line you cannot fund if the seller says no.
Do not skip reserves to look stronger on down payment.
This page is shop plain English.
It is not a loan offer, tax advice, or a guarantee you will qualify for any program.
How to start without touring tonight
Call or message the shop.
Say you want a down payment and cash-to-close walkthrough in plain English.
Bring your savings number, preferred towns, and whether you are looking at FHA, conventional, VA, USDA, or IHCDA lanes.
Browse live listings on Realest.
Message Realest contact.
Read How to buy with the shop.
Ask short questions on Ask Realest at https://realest.net/ask/.
Call Sash at (219) 808-1520.
Office: 112 S. Main St., Suite B, Crown Point. Realest Realty, licensed IN + IL.
What’s your home worth: https://www.realestvalues.com
Ask Realest
Got a short shop question before you tour?
Ask Realest at https://realest.net/ask/ answers short buyer and seller questions in plain English.
Then Realest listings and Realest contact take the live search.
FAQ
How much down payment do I need in Northwest Indiana?
It depends on the loan program, the house price, credit, and reserves. Eligible conventional programs can allow about 3% down. FHA is often 3.5% when you qualify. VA and USDA can be 0% for eligible buyers and properties. Twenty percent is useful for skipping PMI on many conventional loans, but it is not required by law. Your lender’s cash-to-close worksheet is the real number.
Is 20% down required to buy a house in Northwest Indiana?
No. Twenty percent is a common target because it often removes private mortgage insurance on a conventional loan. Many buyers close with less when the loan program and underwriting allow it. Plan for closing costs and reserves on top of the down payment.
How much is 3% or 3.5% down on the June 2026 NWI median?
On the June 2026 NWI MLS median of $299,000, 3% is about $8,970 and 3.5% is about $10,465 for the down payment alone. That median is region context, not your house. Add closing costs, often planned around 2% to 5% of price per CFPB guidance, plus a cushion.
Does Indiana offer down payment assistance?
Yes. Indiana Housing and Community Development Authority (IHCDA) offers purchase programs such as First Step and Next Home through participating lenders. First Step can include down payment assistance up to 6% as a non-forgivable second mortgage for eligible first-time buyers or targeted tracts. Next Home commonly offers 2.5% or 3.5% DPA without a first-time buyer requirement. Income limits, price caps, and repay rules apply. A participating lender confirms eligibility.
Are closing costs part of my down payment?
No. Down payment goes toward the purchase price. Closing costs are separate fees and prepaid items. CFPB guidance often puts closing costs around 2% to 5% of the purchase price, not including the down payment. Ask your lender for a combined cash-to-close estimate.
How do I start a down payment conversation with Realest?
Call Sash at (219) 808-1520 or message Realest contact. Ask for a plain-English cash-to-close walkthrough for your towns and loan lane. Browse Realest listings, use How to buy with the shop, and ask short questions on Ask Realest at https://realest.net/ask/. Office: 112 S. Main St., Suite B, Crown Point. Licensed IN + IL.
Related: Buying and selling at the same time in Northwest Indiana? — cash-to-close when timelines overlap.
Related: Indiana vs Illinois closing costs and title? — cash-to-close beside down payment.
Related: Should I get pre-approved before I tour homes in Northwest Indiana? — buying power beside down payment.